
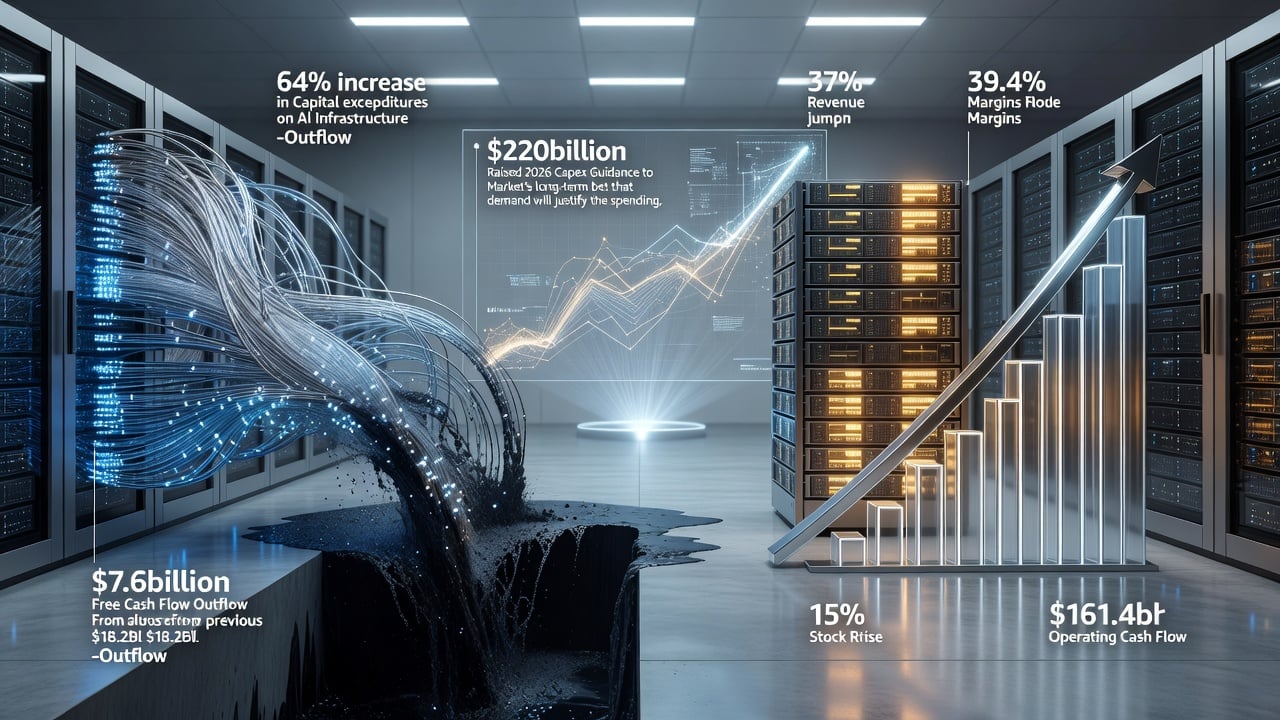
Amazon posted its second-quarter results last week. The numbers showed strength in cloud computing. Yet one line stood out. Trailing twelve-month free cash flow swung to an outflow of $7.6 billion. That compared with an inflow of $18.2 billion a year earlier. A $26 billion reversal. The stock jumped 15 percent anyway.
The shift came from one place. Capital spending. Purchases of property and equipment, net of proceeds, reached $169 billion over the trailing twelve months. Up 64 percent from the prior year. In the quarter alone those outlays hit $54.2 billion against $32.2 billion previously. Operating cash flow told a different story. It climbed 33 percent to $161.4 billion. The business generates plenty of cash. Amazon simply chooses to spend more of it.
Amazon.com Announces Second Quarter Results laid out the details. Net sales rose 20 percent to $200.6 billion. North America grew 16 percent. International added 15 percent. AWS delivered $42.2 billion in revenue. That marked 37 percent growth. The fastest pace in 18 quarters. Operating income for the cloud unit reached $16.6 billion. Up 64 percent. Operating margin expanded to 39.4 percent.
Net income for the period totaled $62.6 billion, or $5.75 per diluted share. A one-time boost helped. The company recorded $53.4 billion in non-operating pre-tax gains tied largely to its investment in Anthropic. Strip that away and the picture still shows solid profitability. Operating income across the company increased to $27.5 billion from $19.2 billion a year ago.
Andy Jassy did not mince words on the earnings call. “AWS is booming, growing 36.7% year-over-year in Q2 — our fastest growth in 18 quarters — and our AI and Chips businesses each eclipsed run rates of more than $25 billion,” the chief executive said, according to the company’s official release. The message landed. Investors heard demand outpacing even the aggressive build-out.
That build-out now carries a bigger price tag. Amazon raised its 2026 capital expenditure forecast to $220 billion from a previous $200 billion target. Higher memory costs played a role. So did the pace of AI infrastructure deployment. Data centers. Networking gear. Custom silicon. All of it aimed at feeding AWS growth and expanding the artificial intelligence offerings that sit atop the cloud platform.
The Motley Fool captured the market’s reaction the day after results. Its article titled “Amazon’s Free Cash Flow Swung $26 Billion in the Wrong Direction. The Stock Rose 15% Anyway.” noted how the negative free cash flow failed to spook anyone. Operating performance looked too good. AWS acceleration looked too convincing. Shares climbed to around $271 in Friday trading. That added roughly $390 billion in market value in a single session.
CNBC offered a similar take. The network reported that “the lavish spending has caused Amazon’s free cash flow to flip into the red.” Yet it framed the increase in capital expenditures as a bet on artificial intelligence infrastructure that management believes will pay off. The story highlighted how AWS growth hit levels not seen in years while the company poured resources into the very technologies driving that demand.
Yahoo Finance went further in a video segment. It asked why Amazon’s stock avoided the fate that met Meta and Alphabet after their own cash flow misses. One commentator pointed out the contrast. Those other tech giants saw shares fall on weaker free cash flow prints. Amazon’s rose sharply. The difference appeared to lie in the narrative. Investors viewed Amazon’s spending as targeted at a high-return opportunity in AI and cloud rather than broad inefficiency.
Recent analysis from TradingKey, published just before the earnings, had already flagged the trend. It noted that trailing twelve-month free cash flow had already shrunk to $1.2 billion entering the quarter. The piece warned that investors would watch closely for signs that AWS momentum could offset the infrastructure costs. Post-earnings, that bet seems to have been validated in the short term.
Conference call slides released by Amazon illustrated the cash flow progression in stark visuals. A bar chart showed free cash flow declining steadily from $18.2 billion at the end of the second quarter of 2025 to negative $7.6 billion by the end of the second quarter of 2026. Operating cash flow kept climbing throughout. The gap simply widened as capital expenditures accelerated.
LinkedIn commentary from analysts reinforced the point. One post described the quarter as demonstrating “a significant divergence between Amazon’s trailing twelve-month operating cash flow of $161.4 billion and TTM free cash flow of -$7.6 billion.” The author argued that the company had prioritized long-term competitive positioning in cloud computing and artificial intelligence over near-term cash metrics.
Guidance for the third quarter struck a cautious tone on revenue while projecting continued operating income growth. Net sales should land between $197 billion and $202 billion. That implies 9 percent to 12 percent growth. The range reflects the tougher comparison from last year’s Prime Day timing. Operating income, however, is expected to reach $22.5 billion to $26.5 billion. That would compare with $17.4 billion in the year-ago period.
So what does this all mean for the longer term? Amazon has made a clear choice. It will invest heavily in the infrastructure needed to maintain leadership in cloud computing and to capture share in the artificial intelligence services layered on top. The bet carries risks. Capital intensity has risen. If demand fails to materialize at expected levels, those outlays could weigh on returns for years.
Yet current trends point the other way. AWS backlog jumped. Customer commitments suggest the new capacity will find buyers quickly. Advertising revenue grew 26 percent in the quarter. Retail operations set records for delivery speed. Grocery and everyday essentials outpaced the broader store business. Multiple engines fire at once.
Wall Street appears prepared to give Amazon the benefit of the doubt. The 15 percent stock pop on a negative cash flow number tells that story clearly. Analysts have raised price targets in recent days. Some now see the company as positioned to compound earnings at high teens rates over the next several years if AWS margins remain elevated and capital spending eventually moderates.
Of course, moderation remains the key question. Management has not signaled any slowdown in infrastructure investment. The $220 billion figure for 2026 exceeds prior plans. And memory costs have risen faster than expected. That suggests further upside risk to capital expenditures in coming quarters.
Investors will watch the next few reports with particular interest. Can AWS sustain growth above 30 percent while margins hold near 40 percent? Will the AI and chips businesses continue scaling beyond their current $25 billion run rates? And perhaps most critically, when might free cash flow turn positive again? The answers will determine whether the market’s current optimism holds.
For now the verdict looks favorable. Amazon generated more operating cash in the trailing twelve months than at any point in its history. It simply deployed that cash into assets expected to produce even greater returns ahead. The $26 billion swing reflects ambition rather than distress. Markets rewarded that ambition last week. They may continue to do so as long as the cloud unit keeps delivering results that match the spending pace.
Other recent coverage echoed similar themes. A YouTube analysis from Synopsis highlighted the $200 billion revenue quarter, 37 percent AWS growth, and dual AI businesses each exceeding $25 billion annualized run rates. It called the raised capital expenditure plan evidence that “the AI bet is paying off.” An Appeconomy Insights post noted that demand still outpaces supply despite the heavy spending, with backlog expanding to $496 billion.
X posts on the day after earnings showed retail and institutional investors digesting the same data points. Several highlighted the contrast with other big tech names that faced share price pressure on cash flow weakness. The consensus seemed to settle on one idea. Amazon’s combination of accelerating cloud growth and massive infrastructure investment sets it apart.
The coming months will test that consensus. Interest rates remain a factor. Higher borrowing costs could make heavy capital programs more expensive. Competition in artificial intelligence intensifies. Microsoft, Google and others pour similar sums into their own data centers and models. Execution matters above all.
Amazon enters this period with advantages. Its cloud platform already hosts a vast ecosystem of enterprise workloads. Its custom chip development gives it cost and performance edges. Its retail and advertising businesses throw off additional cash that can help fund the AI push. The question is whether those advantages prove large enough to absorb the current spending surge without eroding returns.
History offers some precedent. Amazon has spent heavily in the past on fulfillment centers and logistics only to see those investments fuel years of profitable growth. The current AI and cloud build-out may follow a similar path. But scale matters. The dollars involved now dwarf previous capital programs. Patience will be required.
One thing seems clear after last week’s results. Investors have decided to view the negative free cash flow not as a warning sign but as the cost of securing a leading position in the next wave of computing. That perspective drove the stock higher even as the cash flow statement flashed red. Whether that perspective holds over multiple quarters will shape Amazon’s valuation for years to come.


 WebProNews is an iEntry Publication